Wednesday briefing: Is it time to end the Bank of England’s independence?
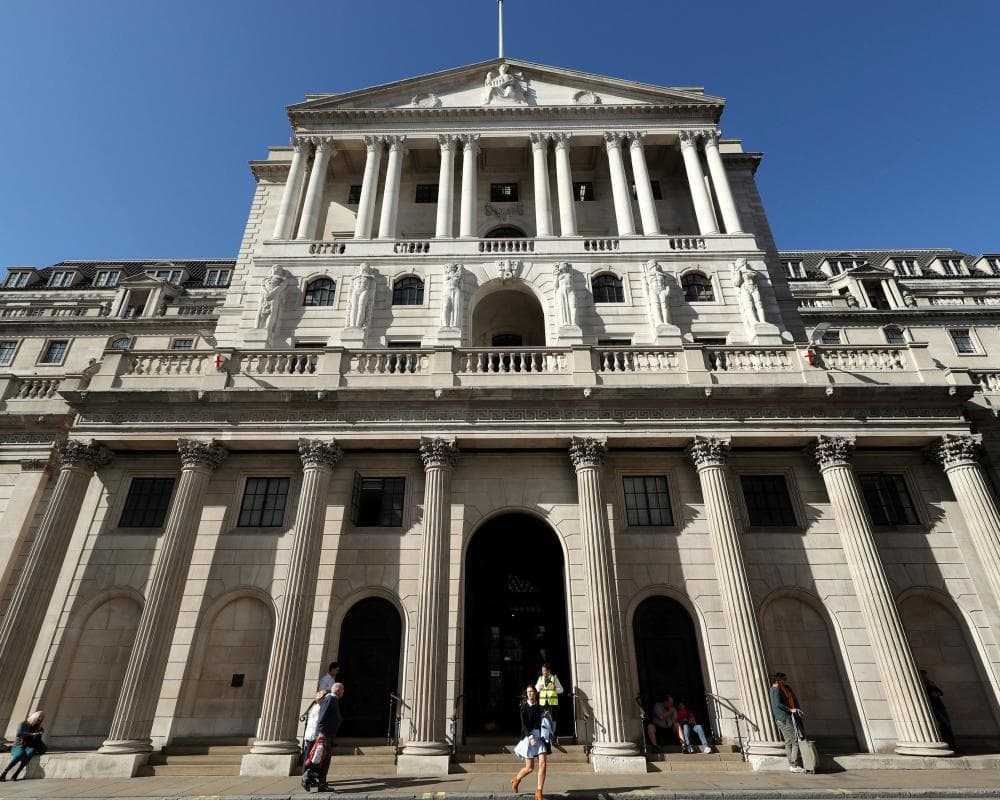
Good morning. There was a time when Bank of England interest rate announcements passed (most of us) by entirely unnoticed. A small rise here; a minor dip there: until May 2022, rates hadn’t climbed above 1% for 13 years. No longer. With rates stuck at 3.75% – and predicted to climb again – the Bank’s decisions are watched closely. Not just by Treasury wonks and trader types, but jobseekers (high rates see higher unemployment) and mortgage holders, both present and aspiring, faced with ramped-up repayments. Rates are reviewed eight times per year by the Bank’s Monetary Policy Committee. But despite it being such a consequential call, its nine unelected members are independent and unaccountable to government. Now parliament’s influential Treasury Committee has launched an inquiry into this relationship. How does the setup work today, and is there an alternative? That’s the subject of today’s First Edition. Plus, we asked three leading progressive economists – Costas Lapavitsas, James Meadway and Ann Pettifor to set out their case for change. Before that, the headlines. Five big stories Europe news | Police have fired teargas at protesters as more than 250,000 pupils, teachers and parents demonstrated across France on the biggest day yet of a campaign for better high school conditions. UK news | John Healey is planning a major intervention to cut energy bills for poorer households in this month’s budget, after ministers became alarmed at forecasts that show bills rising by hundreds of pounds in January. Ebola | Kenya has reported its first-ever Ebola death, as the disease continues to spread rapidly through the north-east of the Democratic Republic of Congo (DRC). UK news | Meta is under investigation for a potential breach of the UK’s digital safety laws after launching a Snapchat-style feature on Instagram. Climate crisis | Drax’s planned datacentre in North Yorkshire could produce nearly double the emissions of all flights out of Gatwick airport each year, an analysis has shown. In depth: Not everyone thinks the status quo is working
The Bank of England has had operational independence since 1997. For 300 years previously, the Bank had many roles, including advising the government. Interest rates were, however, decided by the Chancellor. That was until Gordon Brown, who believed this led to perceptions that short-term political ambition, not the country’s long-term interests, directed monetary policy. He wasn’t alone: by the 1990s, central bank independence had become the global norm. The Bank is tasked with promoting monetary and financial stability. The government dictates a target inflation rate (now 2%), and the Bank sets interest rates it hopes will help achieve this. Since 2009, the Bank has also been in charge of quantitative easing (QE) and tightening (QT). The pitch for Bank of England independence was appealing: limit the influence of ignorant, self-serving MPs, and leave inflation to the experts. This remains integral to conventional economic wisdom. And, it appears to have succeeded. For many of the Bank’s early independent years, inflation in the UK remained low, averaging 2.5% compared to 7.3% between 1967 and 1997. But inflation was similarly restrained in France, Germany, the Netherlands. What impact the Bank had – and how much was the result of global factors – isn’t clear. Certainly, during the early 2022 economic crisis, the UK faced the highest inflation levels in the G7. Inflation has remained above target for most of the last five years, during which time we’ve generally fared worse than our European counterparts (though the most recent data suggests this may be levelling).
Not everyone thinks the status quo is working. In 2023, the House of Lords produced a report (pdf) recommending reforms, such as limiting the Bank’s remit and increasing scrutiny. Given the radical transformation the UK economy has made in the last three decades, a growing chorus of left-wing economists are calling for the government to go further and curtail independence to overhaul the Bank’s mandate. Over the coming months, these arguments will play out in front of the Treasury select committee. Now over to the experts … *** Costas Lapavitsas ‘Money is a public good’ The Bank of England currently serves the interests of the City. Between 2009 and 2021, it kept interest rates at rock bottom and created money on an enormous scale to buy £895bn of bonds, overwhelmingly government debt. This QE propped up the financial system by inflating house and share prices, while productive investment that benefits us all stagnated. In 2022, inflation reached 11.1%, largely fuelled by energy prices and broken supply chains, which interest rates barely affect. Yet the Bank raised rates 14 times – squeezing households and businesses. QE made the Bank bigger, and it has decided to shrink to a more traditional size by selling bonds at prices well below what was paid (higher interest rates cut their value). Much QE money ended up as commercial bank reserves now earning interest at higher rates. The Bank made large losses as billions flowed to banks. In 2024-25 the Treasury, which guaranteed QE against losses, picked up the bill for more than £36bn, while Starmer imposed tight budgets. Amid the cost-of-living crisis, British taxpayers financed the City. Andy Burnham wants to end 40 years of failure. That means tackling Britain’s lopsided economy by rebuilding industrial capacity. The Bank’s independence should be scrapped, and it should be put to work on this. In Reindustrialise Britain, we set out a costed plan. The Bank and the Treasury would work with a new public investment bank providing long-term finance for industry. The Bank would not resume selling bonds at a loss, costing taxpayers billions. It would keep borrowing costs low and stable, ready to finance a measured share of public investment in power, grids, transport and manufacturing. It would accept the investment bank’s bonds on clear terms, so long-term credit is priced for factories, not speculation. All that is perfectly doable. Money is a public good. The institution that creates it should answer to parliament and rebuild industrial strength. Costas Lapavitsas is professor of economics at SOAS, a former Syriza MP, and co-author of Reindustrialise Britain. *** James Meadway ‘We need coordinated responses’ UN figures show food prices across the globe hitting a four-year high, with further rises expected as this year’s “Godzilla” El Niño magnifies the impacts of extreme weather harvest failures. Oil prices are soaring. Inflation everywhere is ticking upwards. For 30 years, mainstream economics has clung to the idea that central banks are uniquely able to manage this. The hard truth is that post-1997, low inflation had more to do with China’s extraordinary industrialisation, keeping goods prices low, than central banker wisdom. The world is now hit by shocks, whether from climate change or geopolitical upsets, that are, in the words of Bank of England ratesetter Swathi Dingra, “beyond the reach of monetary authorities”. Instead of ‘independence’ from government, we need coordinated responses: first, so that central banks change their ratesetting to account for the sources of inflation, leaving interest rates alone when shocks are from sources beyond their reach. Second, governments should support households and businesses, including through the use of strategic price controls, when shocks appear. Right now, they can pass the buck and say inflation isn’t in their purview. Third, countries need to invest in their own supply chains and domestic production, including food, to insulate against future shocks – something lower interest rates can encourage. The Bank is expected to raise interest rates again in November - we shouldn’t let them. Dr James Meadway is director of the Verdant thinktank and former economic adviser to Shadow Chancellor John McDonnell *** Ann Pettifor ‘It makes no sense’ The Bank of England is nationalised, and its staff are on government payroll. The governor is chosen by the prime minister. Governor Andrew Bailey has admitted the Bank cannot do anything about price stability when inflation is imported. Even so, the ‘independent’ Bank intends to raise rates higher – making both private and public investment more expensive, and stalling recovery. It makes no sense: Britain’s fiscal and monetary institutions are at war with each other. The IMF predicts the UK is on course for its worst decade since the 1920s. The private sector is too risk-averse to invest in a weakened economy, and government is effectively forbidden from taking responsibility for economic recovery. Politicians are constrained by ‘fiscal rules’ and by the ‘independence’ of the Bank of England and its 2% inflation target (known as its price stability mandate). This should be abandoned, with full employment and climate consideration its priority. In its place, an Inflation Control Office should be set up. Like France, it would use tools, including a tariff shield and a windfall tax on big energy companies to spend on supporting vulnerable people and lowering the impact of inflation. Next, the Bank should target lower interest rates – vital for both private and public sector investment. Then, as post-2008, the Bank should adopt what are known as targeted longer-term refinancing operations (TLTROs) to give commercial banks the chance to lock in lower interest rates on their loans to customers, while the Bank must offer ‘guidance’ to ensure lending is for productive, not speculative activity. In 1945, when public debt exceeded 200% of GDP, monetary and fiscal coordination gave the government responsibility to address challenges. Today, the state faces many. Maintaining the status quo, and absolving elected governments of responsibility for economic recovery, will only fuel further discontent. Ann Pettifor is an economist and author Have your say Next week, economist Isabella Weber will be here on First Edition answering your questions. From austerity to zero deficits, nothing is too simple. To get in touch hit reply or email first.edition@theguardian.com What else we’ve been enjoying
As a dedicated butter fan, I enjoyed Morwenna Ferrier’s gastronomic tour exploring the cultural rehabilitation of the golden stuff. Libby Robert Reich’s column on the Cornell University case was a good reminder of how a President who acts with impunity against women shapes the broader culture. Poppy Emine Saner’s interview with the legendary Bez, maraca-shaker for the Happy Mondays who says it was harder to give up sugar than cocaine, leaves only one question unanswered: how can he be 62 already? Libby I was stunned by some of our images from the Balkans, based on Irina Rozovsky’s new book. They present a nuanced depiction of a region with a complicated and emotional history. Poppy In this bracing column, Chilean author Ariel Dorfman sets out the lessons from the fall of Pinochet for voters in the US midterms, and warns that reversing Trump’s legacy won’t be simple. Libby Sport
Football | Harry Kane marked becoming England’s joint record cap holder by netting twice as Czechia were crushed 3-0 at Wembley; Sebastien Pocognoli’s first camp as Scotland head coach ended with a grim 2-1 defeat to Slovenia. Tennis | Novak Djokovic capped an outstanding week at the China Open with his first title for nearly a year, and Carlos Alcaraz defeated Jiri Lehecka in the final of the Japan Open to win his first individual title since February. Football | From ‘the new Toni Kroos’ to the US’s next big hope, we select 60 of the best young talents in world football born in 2009. The front pages
The Guardian splashes on “Healey plans £1bn support to bring down energy bills”. The Telegraph leads with “Berlin spy chief leaked UK secrets, MI6 fears”, the Mail says “Tories to slash jobs tax to get young back into work” and the Times has “Badenoch promises tax cuts”. The Financial Times runs with “Oil tanker captains paid $100,000 a month for perilous Hormuz voyages” and top story at The i Paper is “School budgets set for squeeze after blunder over funding teacher pay rises”. The Sun leads on “Murder of royal family GP” and the Mirror says “Too nasty for the nasty party”, as it reports on Nigel Farage and Reform UK. The Latest
Plague outbreak? Russian lab worker dies in Siberia Quarantine measures have been in place in several hospitals in eastern Russia since a 28-year-old laboratory worker, Darya Shipilova, died after falling ill at work following a reported accident at a plague research centre in Siberia. Russia’s health watchdog has said she died of ‘pneumonia of unknown aetiology’, but there is speculation about a possible plague infection. Lucy Hough speaks to Science Weekly co-host Madeleine Finlay. Cartoon of the day | Pete Songi
The Upside A bit of good news to remind you that the world’s not all bad
What if perfumers could create the smell of the world’s most valuable scent ingredient without cutting down the tree that makes it? Agarwood, or oudh, the dark, fragrant resin produced by Aquilaria trees is in such high demand that the wild forests have been devastated. Now advances in AI, which allow it to predict and recreate scents, mean that soon the fragrance industry should be able to reproduce scents and compounds from endangered plants without repeatedly harvesting them. Although technology has long been able to identify molecules in a scent, what’s new is the predictive element. Nevertheless, some conservationists have warned against greenwashing: producing a substitute doesn’t prevent consumers buying the highly prized original – or address other causes of a species’ decline. Sign up here for a weekly roundup of The Upside, sent to you every Sunday Bored at work? And finally, the Guardian’s puzzles are here to keep you entertained throughout the day. Until tomorrow. Quick crossword Cryptic crossword Wordiply